You do not need AED2 million, AED5 million or some other fixed amount just to enter Dubai’s property market.
The amount required to invest in Dubai depends on the property you choose, whether you pay cash or use financing, and how much you need to cover transaction costs beyond the advertised purchase price.
At the affordable end of the market, selected studios in International City are currently advertised from roughly AED295,000–AED310,000, while recent transactions displayed by Property Finder include studios around AED300,000–AED350,000.
Dubai South is another relatively accessible market. Current Property Finder data places studios around AED595,000 on average, although entry-level stock can start around AED465,000 depending on the project and whether the unit is ready or off-plan.
Jumeirah Village Circle sits higher, with current studio asking prices averaging around AED700,000, although some entry-level listings begin at approximately AED425,000.
So, in simple terms, a cash investor may be able to enter Dubai’s property market with a property price in the low AED300,000s.
But that is not the same as saying:
“AED300,000 is all I need.”
Dubai Land Department registration fees, Registration Trustee charges, brokerage where applicable, furnishing, mortgage costs and cash reserves can increase the amount required significantly. DLD’s current completed-sale schedule alone includes a 2% buyer registration portion plus title, map and trustee charges.
The real question should therefore be:
How much total capital do I need for the type of Dubai property investment I want?
Dubai Property Investment Budget at a Glance
| Investment Route | Approximate Capital Position |
|---|---|
| Lower-cost cash purchase | From low AED300k range + transaction costs |
| Dubai South studio | Around AED465k–AED600k+ |
| JVC studio | Around AED425k entry; ~AED700k average |
| AED1m ready investment with mortgage | Around AED400k+ equity, plus costs for an investment-property mortgage |
| AED1m first owner-occupied property for eligible expat | Regulatory down payment can start around AED200k, plus costs |
| Premium 1BR in Dubai Marina | Roughly AED1.8m+ in current market |
| Downtown Dubai 1BR | Roughly AED1.4m–AED3.7m; current average ~AED2.45m |
| Golden Visa property route | At least AED2m qualifying purchase value under current DLD rules |
These are not universal minimums. Property prices change continuously, mortgage approval varies by borrower, and off-plan payment structures differ from project to project.
Is There a Minimum Investment for Dubai Property?
For an ordinary property purchase, Dubai Land Department’s completed-property registration service does not set one universal minimum purchase value that every buyer must meet. The cost of entering the market is therefore driven primarily by the price of the property available to you.
That is different from specific programmes with their own thresholds.
For example, DLD’s current real estate investor Golden Visa route requires qualifying property with a purchase value of at least AED2 million.
So:
Minimum to own qualifying Dubai property: determined by market price.
Minimum headline property value for the current 10-year Golden Visa route: AED2 million.
These should not be confused.
You can own Dubai property worth substantially less than AED2 million.
What Is the Cheapest Way to Enter Dubai Property?
For a cash buyer, lower-priced ready studios are generally one of the most accessible routes.
International City is a useful example.
Property Finder’s current market guide places older International City studios around the low AED300,000 range, with recent examples including registered transactions around AED300,000 and AED325,000.
However, newer International City developments trade much higher, which explains why portal-wide averages can be significantly above the cheapest established stock.
That illustrates an important point:
There is no single “International City price.”
The actual investment budget depends on:
- building
- age
- condition
- unit size
- ready vs off-plan
- current tenancy
- service charges
The cheapest property is also not automatically the best investment.
Example: How Much Cash for a AED353,000 Studio?
Suppose you purchase an International City studio for:
AED353,000
DLD currently lists the buyer’s sale-registration portion at:
2% = AED7,060
Then add the current standard charges applicable to an apartment transaction:
- title deed: AED250
- apartment/villa map: AED250
- Knowledge fee: AED10
- Innovation fee: AED10
- Registration Trustee charge below AED500,000: AED2,000 + VAT.
Using those official buyer-side items, the indicative amount becomes approximately:
AED362,680
before any brokerage, inspection, furnishing, renovation or other transaction-specific expenses.
This example assumes the buyer bears only DLD’s formally listed 2% buyer portion. DLD separately lists another 2% against the seller. The commercial sale agreement should be checked because the parties can structure who ultimately bears certain transaction costs.
Practical lesson
A property advertised at AED353,000 should not be approached with exactly AED353,000 available.
There should be additional capital for the transaction and for ownership after transfer.
How Much Should You Keep Aside for Buying Costs?
For a completed property, DLD currently lists:
| Official Charge | Current Amount |
|---|---|
| Seller registration portion | 2% |
| Buyer registration portion | 2% |
| Title deed certificate | AED250 |
| Apartment/villa map | AED250 |
| Knowledge fee | AED10 |
| Innovation fee | AED10 |
| Trustee fee if property is AED500k+ | AED4,000 + VAT |
| Trustee fee if property is below AED500k | AED2,000 + VAT |
In addition, a buyer may need to budget for:
- brokerage commission if applicable
- bank valuation
- mortgage arrangement costs
- mortgage registration
- inspection
- insurance
- furnishing
- repairs or renovation
Brokerage should not simply be assumed to be one legally fixed percentage; the actual amount should be confirmed in the brokerage agreement.
Do You Need the Full Property Price in Cash?
No, not necessarily.
A buyer can potentially use mortgage financing, subject to eligibility and lender approval.
But investors need to understand an important difference between:
owner-occupied property
and:
investment property.
The Central Bank of the UAE’s current mortgage regulations place different maximum loan-to-value ratios on each category.
How Much Down Payment Does an Expat Need?
For an expatriate buying a qualifying first home for owner occupation, the CBUAE regulatory maximum LTV is currently:
- up to 80% where the property’s value is AED5 million or less
- up to 70% where the property exceeds AED5 million.
That translates into a minimum regulatory equity contribution of:
20% on a qualifying first owner-occupied home of AED5 million or less.
30% above AED5 million.
However, these are maximum permitted LTV ratios—not promises that a bank will lend that much.
A lender can approve less depending on income, credit, age, valuation and internal policy.
Investment Properties Require More Equity
For expatriates buying a second/subsequent home or investment property, the CBUAE mortgage rules set a maximum LTV of 60% of the property value, regardless of value.
That means an investor may need at least:
40% of the property value as equity
before considering transaction and financing costs.
This is particularly relevant to someone buying primarily to rent the property rather than live in it.
Example: AED1 Million Investment Property With a Mortgage
Suppose an expatriate buys a ready investment apartment for:
AED1,000,000
At the 60% regulatory maximum LTV:
Mortgage:
AED600,000
Investor equity:
AED400,000
Now add illustrative official charges:
Buyer-side DLD registration:
AED20,000
Title/map/Knowledge/Innovation:
AED520
Sale Registration Trustee fee:
AED4,000 + VAT
Mortgage registration percentage:
0.25% of AED600,000 = AED1,500.
Before allowing for brokerage, bank charges, valuation, insurance or other mortgage-service costs, the investor is already above AED426,000 of cash commitment in this simplified example.
And DLD’s mortgage-registration process itself can carry additional service-partner and documentation charges.
That means:
“I only need a 40% down payment”
is incomplete budgeting.
What About a AED1 Million First Home?
An eligible expatriate purchasing a AED1 million first owner-occupied property could potentially qualify for up to 80% LTV under the regulatory ceiling.
That would mean:
Property price:
AED1,000,000
20% equity:
AED200,000
An indicative calculation using the current buyer-side DLD registration amount and 0.25% mortgage-registration percentage takes the minimum cash commitment above roughly AED226,000 before brokerage, bank charges and other mortgage-related expenses.
Again, a bank can require a larger down payment than the regulatory minimum.
A Homebuyer Mortgage and an Investment Mortgage Are Not the Same
This distinction can completely change how much money somebody needs.
Consider a AED2 million property.
First owner-occupied purchase
At an 80% maximum LTV, regulatory minimum equity could be:
AED400,000
before fees.
Investment property
At a 60% maximum LTV, regulatory minimum equity would be:
AED800,000
before fees.
The property price is identical.
The cash requirement is very different.
This is why investors should obtain mortgage guidance before reserving a unit.
How Much Money Is Needed for an Off-Plan Property?
Off-plan property works differently.
A developer may allow the purchase price to be paid in stages such as:
- reservation/booking
- instalments during construction
- payment at handover
- post-handover instalments where offered
There is no single Dubai-wide booking percentage that applies to every project.
Payment plans are commercial terms set for individual developments.
The biggest mistake is assuming:
“The booking amount is how much I need to invest.”
It is not.
If the property costs AED1.5 million, the investor has a AED1.5 million contractual property commitment even if only a fraction is required initially.
A Small Off-Plan Deposit Can Hide a Large Future Obligation
Imagine an apartment costs:
AED1,500,000
and only:
AED150,000
is required initially.
That does not mean you purchased a AED150,000 investment.
You committed to a AED1.5 million property and must have a credible plan for the remaining:
AED1,350,000
according to the SPA payment schedule.
Off-plan affordability should therefore be measured using:
total scheduled capital
rather than:
reservation amount.
Can You Mortgage Off-Plan Property?
The CBUAE mortgage framework places a maximum LTV of 50% for property being purchased off-plan, regardless of purchaser category, value or purpose.
However, actual off-plan mortgage availability depends on:
- lender
- project
- construction progress
- developer
- buyer eligibility
Many off-plan purchases instead rely primarily on the developer payment plan during construction.
A payment plan and a bank mortgage are different financing structures.
How Much for a Dubai South Investment?
Dubai South is one of the more accessible newer property markets.
Current Property Finder data indicates:
| Unit | Current Market Indicator |
|---|---|
| Studio | ~AED595,000 |
| 1-bedroom | ~AED1.1m |
| 2-bedroom | ~AED1.8m |
| 3-bedroom | ~AED2.5m |
Current studio entry inventory can begin around AED465,000 depending on the building or project.
Cash investor
A buyer purchasing a AED595,000 studio outright should budget beyond AED595,000 for registration and other acquisition costs.
Mortgage investor
If it is classified as an investment property and financed under a 60% maximum LTV, the regulatory equity requirement alone could be around:
AED238,000
before transaction costs.
Whether a particular lender will finance the property at that ratio is a separate question.
How Much for a JVC Investment?
JVC is a step up in pricing but remains accessible relative to central Dubai.
Current Property Finder data puts the average JVC studio around:
AED700,000
with entry stock beginning around:
AED425,000.
JVC is therefore relevant to investors with purchase budgets roughly between the more affordable older communities and premium central Dubai.
For a AED700,000 investment apartment using a 60% mortgage:
40% equity alone would equal:
AED280,000
before DLD, bank and transaction costs.
A cash purchaser would need the full property price plus those additional expenses.
How Much for Dubai Marina?
Dubai Marina requires substantially more capital.
Current Property Finder data places the average one-bedroom sale price around AED1.86 million, although the community spans older affordable towers and much newer premium developments.
If an investor purchases a AED1.86 million Marina apartment using the maximum 60% investment-property LTV:
40% equity alone is approximately:
AED744,000
before transaction and financing costs.
That illustrates how quickly the required capital increases when moving from affordable Dubai communities into established waterfront districts.
How Much for Downtown Dubai?
Downtown Dubai is firmly in the premium market.
Current Property Finder one-bedroom data shows:
Average asking price: approximately AED2.45 million
Average asking price per square foot: approximately AED2,744.
Across the wider Downtown market, one-bedroom asking prices can range from around AED1.4 million to above AED3.7 million depending on building, view and product.
For a AED2.45 million investment apartment using a maximum 60% LTV:
40% equity would already be approximately:
AED980,000
before transaction costs.
That means an investor approaching Downtown with AED200,000–AED300,000 in available capital may find the financing structure very difficult unless the purchase is structured differently.
What Can Different Dubai Property Budgets Buy?
Current market evidence gives a rough idea of how investment options expand as capital increases.
AED300,000–AED500,000 property-price budget
Potential opportunities can include:
- older International City studios
- selected entry-level JVC studios
- selected lower-priced Dubai South stock
International City currently offers some of the lowest established freehold apartment prices, with selected studios around AED300,000.
At this level, building condition and service charges deserve careful attention.
AED500,000–AED800,000
The choice broadens to include:
- International City
- Dubai South studios
- JVC studios
- selected established affordable communities
This budget can provide greater choice in building age and quality.
Around AED1 million
At roughly AED1 million, investors can start comparing:
- JVC
- Dubai South
- Sports City
- Dubai Silicon Oasis
- Discovery Gardens
- selected Al Furjan stock
The strategy can shift from simply finding the cheapest unit to balancing:
yield + building quality + resale demand.
AED1.5 million–AED2 million
The buyer can begin comparing:
- JLT
- Dubai Marina
- Dubai Hills Estate
- Dubai Creek Harbour
- Business Bay
- larger units in high-yield areas
This is where location and property quality can become more important than maximum yield.
AED2 million+
This budget opens much more of Dubai’s premium property market and can also potentially meet the headline property-value requirement for the current 10-year Golden Visa route.
But AED2 million should not be spent solely because it matches a visa threshold.
The property still needs to make financial sense.
Does AED2 Million Guarantee a Golden Visa?
No.
AED2 million is the current DLD headline purchase-value threshold for its 10-year real estate investor Golden Visa service, subject to the applicable conditions and documentation.
DLD’s current page also states that where property is mortgaged, the investor needs a bank letter showing the required paid amount.
So the Golden Visa should be treated separately from the question:
How little can I spend to own Dubai property?
Those are completely different thresholds.
Should You Use All Your Available Cash to Buy?
Usually, the more useful investment budget is not:
all the money you have.
It is:
capital available after maintaining sufficient liquidity for ownership expenses.
Property owners may face:
- service charges
- repairs
- vacancy
- furnishing replacement
- insurance
- mortgage payments
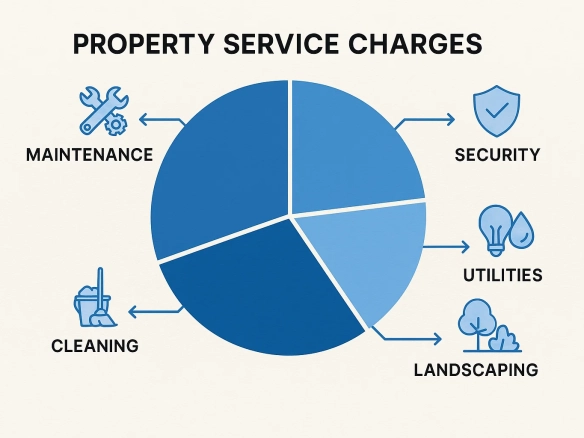
DLD’s Service Charge Index allows buyers to check RERA-approved charges for the specific jointly owned property, including the current 2026 budget year.
A buyer who uses every available dirham on transfer day can create unnecessary financial pressure later.
Service Charges Should Be Part of Your Budget
Suppose you buy a studio because it appears affordable.
Purchase price:
AED500,000
But annual service charges are:
AED12,000
That is:
2.4% of the purchase price every year
before maintenance, vacancy or management.
A slightly more expensive apartment with significantly lower service charges can sometimes produce the better long-term investment.
Use the exact building’s RERA-approved figure rather than a generic Dubai estimate.
Furnishing Can Add Thousands to the Investment Budget
A ready apartment may be:
- furnished
- partly furnished
- completely empty
If the strategy involves a furnished rental, initial capital may need to cover:
- furniture
- appliances
- curtains
- kitchen equipment
- décor
- internet setup
These costs vary enormously by property and furnishing standard.
They should therefore be treated as a property-specific budget rather than assigned one universal Dubai figure.
Renovation Can Make a Cheap Property Expensive
A low-priced older unit may look attractive until renovation costs are included.
Suppose:
Purchase price: AED400,000
Renovation: AED70,000
Furniture: AED30,000
The effective property capital is already:
AED500,000
before acquisition costs.
Compare that amount against a better-condition property rather than focusing only on the original asking price.
Cash vs Mortgage: Which Requires Less Money?
A mortgage clearly reduces the amount needed on purchase day compared with paying the full property price.
But it also introduces:
- interest
- bank fees
- valuation
- mortgage registration
- monthly debt service
Dubai Land Department currently charges 0.25% of the mortgage amount for an ordinary mortgage, in addition to applicable title and service-partner charges.
So mortgage investors should calculate:
cash required upfront
and:
monthly cash flow after financing.
A property can be affordable to purchase yet produce poor annual cash flow after the mortgage payment.
How Much Money Should a First-Time Dubai Investor Have?
There is no single number, but a practical framework is:
Low-budget cash investor
Think in terms of:
low AED300,000s upward
for the property itself in the most affordable established segments, plus acquisition costs and reserves.
Mortgage investment-property buyer
Think in terms of:
at least roughly 40% equity
under the CBUAE’s regulatory maximum for expatriate investment property, plus transaction, bank and ownership costs.
Premium-market investor
AED1.5 million–AED3 million opens significantly more established and central communities.
Current Dubai Marina one-bedroom averages are around AED1.86 million, while Downtown one-bedrooms average around AED2.45 million.
Golden Visa-focused investor
Start with the current AED2 million qualifying purchase-value threshold, then add all acquisition and financing costs separately.
Do Not Confuse Affordability With Investment Quality
A AED300,000 apartment can be too expensive.
A AED3 million apartment can be attractively priced.
The number alone does not determine value.
An investor needs to compare:
- price per square foot
- recent transactions
- annual rent
- service charges
- condition
- vacancy
- future supply
- resale demand
DLD’s Dubai REST platform gives property owners and market participants access to information including current property prices, rental return, service charges, sale indices and project information.
The correct investment is the one whose economics work at the actual purchase price.
Why Your Budget Should Include a Cash Reserve
A property investment should not depend on perfect conditions every month.
Suppose the tenant leaves.
The property needs painting.
An appliance fails.
The next tenant takes six weeks to arrive.
A buyer with no reserve may be forced to make poor decisions or sell at the wrong time.
A more robust budget includes money for:
- vacancy
- repairs
- service charges
- mortgage payments
- unexpected ownership expenses
The reserve will depend on the property and financing structure rather than one universal percentage.
Off-Plan Buyers Need an Instalment Reserve Too
Off-plan buyers face a different cash-flow risk.
Future instalments may be due:
- quarterly
- at construction milestones
- at handover
An investor should know where every instalment is coming from before signing the SPA.
Do not assume that appreciation will allow the property to be resold before the next payment.
That turns an investment plan into a speculative dependency.
How to Calculate Your Real Dubai Property Budget
Use this formula:
Cash purchase
**Property price
- buyer-side DLD costs
- agreed additional transaction costs
- furnishing/renovation
- ownership reserve
= Total cash requirement**
Mortgage purchase
**Down payment
- DLD costs
- mortgage registration
- bank costs
- other transaction costs
- furnishing/renovation
- cash reserve
= Total upfront requirement**
Off-plan purchase
**Initial payment
- DLD/registration obligations
- all scheduled construction instalments
- handover payment
- furnishing
- reserve
= Total investment commitment**
The last figure is much more useful than the marketing phrase:
“Book from only AED50,000.”
Common Budgeting Mistakes
Thinking the listing price is the full cost
It is not. DLD and other acquisition expenses need to be added.
Believing AED2 million is the minimum to buy
It is not. AED2 million relates to the current headline Golden Visa property threshold, not ordinary property ownership.
Treating a 10% off-plan booking as the total investment
The investor remains responsible for the entire SPA payment schedule.
Assuming every mortgage requires only 20%
For expatriate investment property, the CBUAE maximum LTV is currently 60%, implying 40% equity at the regulatory ceiling.
Forgetting mortgage registration
DLD currently charges 0.25% of the mortgage value for an ordinary mortgage.
Spending every available dirham
Property requires ongoing liquidity.
Ignoring service charges
Use DLD’s official Service Charge Index.
Buying the cheapest property automatically
Low acquisition cost can come with weak building quality, poor liquidity or expensive maintenance.
Frequently Asked Questions
What is the minimum amount needed to invest in Dubai property?
There is no single DLD purchase-value minimum for an ordinary completed-property sale. At the low end of today’s market, selected International City studios can trade around the low AED300,000 range, but buyers need additional money for transaction and ownership costs.
Can I invest AED300,000 in Dubai property?
Potentially. Selected older International City studios have recently traded or been marketed around AED300,000–AED350,000. Inventory changes constantly, and your total cash requirement will be higher after purchase costs.
Can I buy Dubai property with AED500,000?
Yes, there are property options around this level. Current examples include entry-level Dubai South studios from roughly AED465,000 and selected JVC studios starting around AED425,000. These are asking-market indicators rather than guaranteed purchase prices.
How much deposit do I need for a Dubai mortgage?
It depends on the purchase category. For expatriates, the current CBUAE maximum LTV is 80% for a qualifying first owner-occupied property worth AED5 million or less, implying 20% equity. For second/subsequent or investment property, maximum LTV is 60%, implying 40% equity.
How much down payment is needed for off-plan property?
Developer payment plans vary, so there is no universal booking percentage. If bank mortgage financing is used for off-plan property, the CBUAE framework caps LTV at 50%.
How much extra should I budget beyond the property price?
DLD currently lists a 2% buyer registration portion, plus title deed, map, Knowledge, Innovation and Registration Trustee charges. Buyers may also incur brokerage, financing, valuation, inspection, furnishing and other costs.
Is the Dubai property registration fee 4%?
DLD’s current completed-sale schedule lists 2% against the seller and 2% against the purchaser, producing a combined 4%. Buyers should review the transaction agreement to determine the commercial allocation of costs.
How much money do I need for a AED1 million investment property with a mortgage?
For an expatriate investment-property mortgage at the regulatory maximum 60% LTV, at least AED400,000 would represent the equity portion. Once current DLD purchase and mortgage-registration expenses are added, the simplified upfront requirement moves above roughly AED426,000 before brokerage, bank fees and other costs.
How much do I need for a AED1 million first home?
For an eligible expatriate purchasing a first owner-occupied home worth AED5 million or less, the current maximum LTV is 80%, meaning regulatory minimum equity can be 20%, or AED200,000 on a AED1 million property. Additional transaction and mortgage expenses still apply.
How much money is needed for a Golden Visa property?
DLD’s current 10-year real estate investor Golden Visa service requires qualifying property with a purchase value of at least AED2 million, subject to the current requirements.
Is AED1 million enough for a good Dubai investment?
It can provide access to several mainstream apartment markets, including JVC, Dubai South and other affordable or mid-market communities. Whether a particular property is good depends on rent, service charges, building quality, purchase price and future supply.
Is it better to buy one AED1 million apartment or two AED500,000 apartments?
There is no universal answer. Two units can diversify tenant risk but also create two sets of transaction, furnishing, maintenance and management obligations. One better-quality unit may provide stronger resale liquidity. Compare net returns rather than unit count.
Should I buy cash or use a mortgage?
Cash generally produces stronger rental cash flow and avoids financing costs. Mortgages reduce the upfront capital requirement but introduce interest and debt-service risk. The best choice depends on the property’s net return and the investor’s liquidity.
How Much Should You Really Have Before Investing in Dubai?
The lowest Dubai property prices can make the market look surprisingly accessible.
Selected older studios can still trade in the low AED300,000 range.
Dubai South offers newer entry-level stock from around the mid-AED400,000s, while JVC studios currently start in a similar broad range but average closer to AED700,000.
At the other end of the market, current one-bedroom averages move toward AED1.86 million in Dubai Marina and AED2.45 million in Downtown Dubai.
So there is no one answer to how much money you need.
A useful way to think about it is:
AED300k–AED500k property budget: entry-level studio market.
AED500k–AED1m: wider affordable-investment choice.
AED1m–AED2m: mainstream and selected premium communities.
AED2m+: premium market plus potential access to the current Golden Visa property threshold.
But the property price is only stage one.
Your actual investment budget must include:
property + acquisition + financing + setup + reserve.
For mortgage buyers, determine whether the purchase will be classified as owner-occupied or investment property before estimating the down payment.
For off-plan buyers, calculate every instalment through handover rather than focusing on the booking amount.
For cash buyers, keep enough liquidity after transfer to deal with service charges, maintenance and vacancy.
And for every buyer, ask a more important question than:
“Can I afford to buy this property?”
Ask:
“Can I comfortably own this property if rent is lower than expected, an expense appears or I need to hold it longer than planned?”
That is a far more useful measure of whether the investment budget is sufficient.
HAMZ International Real Estate can help buyers compare Dubai properties across different budget levels, calculate realistic acquisition costs, evaluate ready and off-plan opportunities and identify investment options aligned with their available capital and intended strategy.