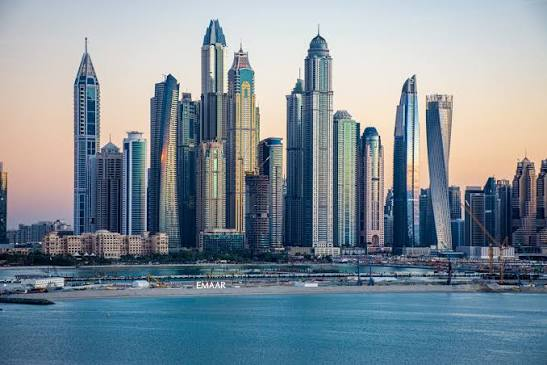
Dubai property investment is accessible to international buyers, including people who do not live in the UAE. Foreign investors can acquire freehold property in designated areas, purchase completed or off-plan units, earn rental income and sell their assets through the Dubai Land Department’s regulated registration system.
The opportunity is substantial, but international investors face risks that local buyers may find easier to manage. These include remote due diligence, currency movements, unfamiliar contracts, optimistic rental projections and reliance on agents or property managers.
Strong investment performance does not come from buying any new apartment in a well-known Dubai location. It depends on acquiring the right property at a defensible price, controlling ownership costs, attracting reliable tenants and preserving resale liquidity.
This guide explains what an international investor should know before buying property in Dubai, from ownership and market selection to financing, tax, residency and exit planning.
Dubai Property Investment at a Glance
| Question | General position |
|---|---|
| Can an international investor buy property in Dubai? | Yes, in designated foreign-ownership areas |
| Is UAE residency required? | No |
| Can a non-resident obtain a mortgage? | Potentially, through selected lenders |
| Can the purchase be completed remotely? | Often, subject to the transaction process |
| Can the property be rented out? | Yes |
| Is there an annual residential property tax? | Dubai does not impose a conventional annual property tax |
| Is there a registration charge? | Yes; the standard DLD sale-registration charge totals 4% |
| Can the property qualify the investor for residency? | Potentially, if the current eligibility conditions are met |
| Is rental income guaranteed? | No |
| Is capital appreciation guaranteed? | No |
Foreign ownership, visa eligibility, financing and investment performance are separate questions. Approval in one area does not guarantee another.
Why International Investors Choose Dubai
Dubai has developed into one of the world’s most internationally accessible property markets.
Dubai Land Department reported that real estate transactions reached approximately AED 252 billion in the first quarter of 2026, an increase of 31%. DLD also reported foreign investment value of AED 148.35 billion during the period, reflecting continued international participation.
Several factors support Dubai’s appeal.
Foreign ownership
Foreign residents and overseas buyers may acquire freehold ownership in designated areas.
International tenant demand
Dubai attracts professionals, entrepreneurs, families, students and tourists. This creates demand across long-term residential, corporate and short-term rental segments.
No conventional annual property tax
Dubai does not charge residential owners a recurring property tax comparable to those levied in many international cities.
Owners must still pay service charges, insurance, maintenance and management costs.
Modern registration system
Property sales, mortgages and off-plan registrations are recorded through Dubai Land Department. Buyers can also access services and project information through Dubai REST.
Global connectivity
Dubai’s airports, business environment and location between Europe, Asia and Africa support demand from residents and international businesses.
Property-linked residency possibilities
Qualifying investors may apply for UAE residency under the applicable property-investment requirements. Ownership alone does not automatically grant residency.
Where Can International Investors Buy?
Foreign buyers may purchase in areas designated for foreign ownership.
Popular freehold investment locations include:
- Downtown Dubai
- Business Bay
- Dubai Marina
- Palm Jumeirah
- Dubai Hills Estate
- Dubai Creek Harbour
- Mohammed Bin Rashid City
- Jumeirah Village Circle
- Jumeirah Beach Residence
- Dubai Harbour
- Bluewaters Island
- Dubai Islands
- Dubai South
- Emaar South
- Arabian Ranches
- Emirates Hills
- Jumeirah Golf Estates
- DAMAC Hills
- Meydan
The specific unit and plot should be checked. Do not assume that every property within a broadly defined community has the same ownership status.
Choose the Investment Strategy Before the Property
Many investors begin with listings. A stronger approach begins with the intended return.
Long-term rental investment
A long-term rental property is leased under a conventional annual tenancy.
It may suit investors seeking:
- More predictable occupancy
- Lower operational involvement
- Reduced furnishing requirements
- Fewer tenant turnovers
- Simpler remote management
Performance depends on tenant demand, achievable rent, service charges, maintenance and vacancy.
Short-term rental investment
A furnished property can be offered as a licensed holiday home.
It may provide higher gross revenue during strong periods, but the investor must account for:
- Seasonal demand
- Furnishing
- Utilities
- Cleaning
- Platform fees
- Holiday-home management
- Guest turnover
- Tourism compliance
- Maintenance
- Periods of low occupancy
A high nightly rate does not necessarily produce a high net return.
Capital-growth investment
Some investors prioritise future appreciation rather than immediate yield.
Possible drivers include:
- Infrastructure
- Community completion
- New transport connections
- Waterfront activation
- Retail and hospitality openings
- Limited comparable supply
- Improvement in the area’s resident profile
Capital growth remains uncertain. Buyers should not pay today for every future benefit as though it were already delivered.
Off-plan appreciation strategy
An investor may buy during construction and sell before or after completion.
This strategy depends on:
- Entry price
- Developer reputation
- Payment plan
- Construction progress
- Assignment rules
- Competing supply
- Market conditions
- DLD and developer costs
Off-plan resale is not guaranteed. The developer may require a minimum percentage of the purchase price to be paid before permitting assignment.
Personal-use investment
Some international investors want a property that can be used periodically while retaining long-term value.
This can justify choosing a more distinctive location or larger unit, but personal preferences should not be confused with tenant or resale demand.
Ready Property or Off-Plan?
| Factor | Ready property | Off-plan property |
|---|---|---|
| Inspection | Actual unit can be inspected | Based mainly on plans, show units and construction progress |
| Rental income | Potentially available after transfer | Begins after completion and handover |
| Payment | Usually required at transfer | Commonly spread across a payment plan |
| Construction risk | Limited | Delay and execution risk remain |
| Price evidence | Comparable completed transactions may exist | Launch prices may be harder to benchmark |
| Service charges | Historical charges may be available | Usually estimated |
| Financing | More conventional mortgage options | Depends on project and construction stage |
| Registration | Title transfer | Initial registration followed by title deed after completion |
| Resale | Based on existing market liquidity | Subject to developer and contract restrictions |
A ready property often suits an investor who prioritises income visibility and physical due diligence. Off-plan property may suit an investor seeking staged payments and exposure to future community growth.
Apartment or Villa?
Apartments
Apartments generally offer:
- Lower entry prices
- Larger tenant pools
- Easier remote management
- Strong demand in central districts
- Greater choice across budgets
Potential disadvantages include:
- Service charges
- Building-level competition
- Limited control over management
- High supply in some communities
- Reliance on lifts and shared facilities
Villas and townhouses
Villas may offer:
- Family-oriented demand
- Longer tenant stays
- Land component
- Greater privacy
- Lower direct competition within some subcommunities
Potential disadvantages include:
- Higher acquisition cost
- Greater maintenance exposure
- Landscaping and exterior upkeep
- Smaller tenant pool
- Potentially longer vacancy
The better investment is the property with the strongest net return, demand and exit liquidity—not automatically the cheaper apartment or larger villa.
How to Compare Dubai Investment Areas
International investors should compare communities using the same criteria.
| Factor | What to investigate |
|---|---|
| Entry price | Registered sale evidence, not only asking prices |
| Rent | Achieved or realistically attainable rent |
| Tenant profile | Families, professionals, students, tourists or corporate tenants |
| Service charges | Current charges and likely impact on net income |
| Vacancy | Competing listings and average leasing time |
| Supply pipeline | Future units competing for tenants and buyers |
| Transport | Roads, Metro, airport and employment access |
| Amenities | Schools, retail, healthcare, parks and leisure |
| Building quality | Maintenance, facilities and management |
| Exit liquidity | Transaction volume and likely resale audience |
A popular community can still contain poorly performing buildings. Building selection is often as important as area selection.
Asking Prices Versus Registered Prices
Online listings show what sellers hope to achieve. They do not prove the value at which comparable properties have completed.
Before buying, compare:
- DLD-registered transactions
- Price per square foot
- Unit type
- View
- Floor
- Condition
- Furnishing
- Parking
- Payment plan
- Handover date
- Tenancy status
An off-plan property with a long payment plan may carry a higher headline price than a similar unit purchased with a shorter payment period. Compare the economic value rather than the advertised instalment.
Dubai Land Department provides transaction, rent, project, valuation, developer and unit information through its real estate data services.
Gross Yield Versus Net Yield
Gross yield is commonly calculated as:
If an apartment costs AED 1 million and generates AED 75,000 in annual rent:
This does not represent the investor’s actual return.
Net yield deducts recurring costs:
Possible deductions include:
- Service charges
- Property management
- Maintenance
- Vacancy
- Leasing commission
- Insurance
- Furnishing replacement
- Utility costs
- Holiday-home operating expenses
- Mortgage interest
Example net-yield calculation
| Item | Annual amount |
|---|---|
| Rent | AED 75,000 |
| Service charges | AED 13,000 |
| Management | AED 3,750 |
| Maintenance allowance | AED 2,500 |
| Vacancy allowance | AED 3,750 |
| Net operating income | AED 52,000 |
If the investor’s acquisition basis is AED 1.07 million after relevant purchase costs:
This example demonstrates why a marketed 7.5% gross yield can produce a substantially lower net return.
Calculate the Complete Purchase Cost
The property price is only one part of the investment.
Typical acquisition costs
| Cost | Indicative basis |
|---|---|
| DLD sale-registration fee | 4% in total under the official schedule |
| Registration trustee | AED 4,000 plus VAT for sales of AED 500,000 or more |
| Trustee below AED 500,000 | AED 2,000 plus VAT |
| Title deed | AED 250 |
| Apartment or villa map | AED 250 |
| Knowledge and innovation fees | AED 10 each where applicable |
| Agency commission | Commonly negotiated as a percentage plus VAT |
| Developer NOC | Varies |
| Legal or conveyancing review | Varies |
| Property inspection | Varies |
| Mortgage registration | 0.25% of mortgage value |
| Bank valuation and arrangement | Lender-specific |
| Currency transfer | Bank and provider-specific |
The statutory DLD schedule allocates 2% to the seller and 2% to the buyer. Sale agreements frequently require the buyer to pay the full 4%, so the contractual allocation should be confirmed.
An international cash buyer should often reserve approximately 6%–8% above the purchase price for acquisition costs. A mortgaged or furnished purchase may require more.
Example International Investment Budget
For a ready apartment priced at AED 1.5 million:
| Item | Illustrative amount |
|---|---|
| Purchase price | AED 1,500,000 |
| DLD fee at 4% | AED 60,000 |
| Trustee fee plus VAT | AED 4,200 |
| Title deed and map | AED 500 |
| Agency commission at 2% plus VAT | AED 31,500 |
| Inspection and legal review | Variable |
| Furnishing | Variable |
| Initial service charges | Variable |
| Total before variable costs | AED 1,596,200 |
This is a planning example, not a transaction quotation.
Step-by-Step Buying Process
1. Set the investment objective
Decide whether the priority is:
- Rental income
- Capital appreciation
- Personal use
- Residency
- Portfolio diversification
- Currency diversification
- Future relocation
Set a target holding period and acceptable risk level.
2. Establish the full budget
Include acquisition costs, furnishing, reserves and ongoing ownership expenses.
Do not use the entire investment budget as the property-price ceiling.
3. Choose the ownership structure
An international investor may buy:
- Personally
- Jointly
- Through an eligible company
Personal ownership is often simplest for a single residential investment. Company ownership may suit joint investors or larger portfolios but creates tax, licensing, accounting and banking obligations.
Obtain cross-border tax and legal advice before choosing.
4. Verify the broker
Use a broker licensed by the Real Estate Regulatory Agency.
Verify:
- Brokerage
- Individual broker
- Property advertising permit
- Developer
- Commission
- Who represents each party
- Any financial relationship with the seller or developer
5. Analyse the property
Compare:
- Registered price evidence
- Realistic rent
- Service charges
- Vacancy
- Building condition
- Tenant demand
- Competing supply
- Maintenance history
- Planned construction
- Resale liquidity
6. Inspect independently
If possible, visit the property.
If buying remotely, appoint an independent inspector or surveyor and request a live video walkthrough.
For a ready property, inspect:
- Internal condition
- Water damage
- Air conditioning
- Plumbing
- Electrical systems
- View
- Noise
- Parking
- Common areas
- Building management
7. Review the legal documents
For a resale property, verify:
- Seller identity
- Title deed
- Mortgage
- Tenancy
- Service-charge balance
- Developer NOC requirements
- Sale agreement
For an off-plan property, verify:
- Developer
- Project
- Escrow account
- SPA
- Payment plan
- Initial registration
- Handover provisions
- Assignment restrictions
8. Arrange payment or financing
Confirm:
- Deposit
- Transfer currency
- Beneficiary
- Source-of-funds evidence
- Bank processing time
- Mortgage pre-approval
- Currency-conversion cost
Never transfer funds to an unverified account.
9. Complete registration
Completed-property transfers are registered through DLD and an authorised real estate registration trustee.
Off-plan sales are entered in the provisional register, with the final title deed issued after completion and handover requirements are satisfied.
10. Establish management
Before completion, decide who will:
- Market the property
- Select tenants
- Register the tenancy
- Collect rent
- Handle maintenance
- Pay service charges
- Inspect the unit
- Report income and expenses
Can an International Investor Buy Remotely?
Often, yes.
Possible routes include:
- Remote registration
- Eligible digital-sale services
- A legally valid power of attorney
- Personal attendance for final transfer
DLD has introduced remote registration procedures involving electronic document checks and audiovisual identity verification.
A buyer should confirm the current procedure for the specific transaction. Some digital services may require UAE Pass, and mortgage lenders may impose separate signing requirements.
A foreign power of attorney may require:
- Notarisation
- Authentication
- UAE diplomatic legalisation
- UAE attestation
- Legal Arabic translation
Documents International Investors Need
A non-resident individual will commonly need:
- Valid passport
- Proof of residential address
- Contact information
- Tax-residence details
- Source-of-funds evidence
- Bank statements
- Signed sale documents
- Power of attorney if represented
A mortgage applicant may also need:
- Employment letter
- Salary evidence
- Tax returns
- Credit report
- Business accounts
- Existing liability details
- Property valuation
A company buyer needs incorporation, licensing, constitutional, shareholder, signatory and beneficial-owner documents.
Can International Investors Get a Mortgage?
Potentially. Selected UAE banks provide mortgages to non-residents, while resident expatriates generally have wider access.
Banks may assess:
- Nationality
- Country of residence
- Income
- Age
- Employment
- Business ownership
- Credit history
- Existing debts
- Property type
- Valuation
- Currency of earnings
Non-residents may face:
- Higher deposits
- Lower loan-to-value ratios
- Fewer eligible properties
- Higher minimum income
- More compliance documents
Obtain mortgage pre-approval before signing an unconditional agreement.
Pre-approval is not final approval. The property must still pass valuation and legal review.
Currency Risk
Dubai property is priced in UAE dirhams. The dirham is pegged to the US dollar, so investors whose income or capital is held in another currency are exposed to movements against the dollar.
Currency risk can affect:
- Deposit cost
- Instalment amounts
- Mortgage repayments
- Rental-income conversion
- Sale proceeds
- Reported home-currency return
An investor may earn a positive return in dirhams but record a lower return after conversion into their home currency.
Maintain a currency contingency, particularly for off-plan purchases with multi-year payment plans.
Transferring Funds Safely
Before transferring money:
- Verify the beneficiary independently
- Confirm the IBAN and SWIFT code
- Use the correct property reference
- Keep source-of-funds evidence
- Ask who bears international banking fees
- Allow time for compliance checks
- Obtain a formal receipt
Off-plan payments should follow the verified project escrow instructions.
For a resale property, the final balance should be handled through the approved completion structure. Do not pay the full purchase price directly to the seller before title transfer without appropriate transaction protection.
Rental Strategy for Overseas Investors
Long-term rental
Advantages include:
- More stable occupancy
- Simpler operations
- Fewer turnovers
- Lower furnishing demands
- More predictable income
Risks include:
- Tenant default
- Vacancy between leases
- Maintenance
- Rental-market changes
- Legal notice requirements
Dubai tenancy contracts should be registered through Ejari.
Short-term rental
Advantages include:
- Flexible personal use
- Potentially higher seasonal revenue
- Dynamic pricing
- Access to tourism demand
Risks include:
- Seasonal occupancy
- Higher management fees
- Furnishing costs
- Utilities
- Cleaning
- Guest damage
- Platform charges
- Regulatory compliance
A property must comply with Dubai’s holiday-home requirements. Use a licensed operator if outsourcing management.
Property Management From Abroad
An overseas investor may appoint a licensed property manager to handle:
- Marketing
- Viewings
- Tenant screening
- Contract preparation
- Ejari support
- Rent collection
- Inspections
- Maintenance
- Renewal
- Move-out
- Owner statements
Ask whether the management fee includes:
- Leasing commission
- Maintenance supervision
- Emergency support
- Inspection reports
- Utility management
- Legal notices
- Holiday-home operations
- Tax or accounting reports
A low headline fee may exclude essential services.
UAE Tax Considerations
Dubai does not impose a conventional annual residential property tax.
An individual’s UAE property investment income may also fall outside UAE Corporate Tax when the property is held in a personal investment capacity and the relevant conditions are satisfied.
However, the treatment may differ where:
- The property is held through a company
- The investor conducts a licensed business
- The property is commercial
- VAT applies
- The activity goes beyond personal investment
The investor’s home country may tax:
- Rental income
- Capital gains
- Foreign assets
- Inheritance
- Company distributions
- Currency gains
Dubai’s local treatment does not override tax obligations elsewhere.
Property Investment and UAE Residency
Buying property does not automatically make an international investor a UAE resident.
The current Golden Residency framework recognises real estate investment of at least AED 2 million as a qualifying category, subject to official conditions.
Eligibility may depend on:
- Registered property value
- Investor’s ownership share
- Mortgage status
- Amount paid
- Number of properties
- Completion status
- Immigration documentation
- Health insurance
Do not rely on a developer’s visa promise. Confirm the current rules with DLD and the relevant immigration authority before purchasing.
If the property is owned through a company, the shareholder should not assume that the company’s title deed will qualify them personally.
Off-Plan Due Diligence
Before purchasing off-plan, verify:
- Developer licence
- Project registration
- Escrow account
- Unit registration
- Construction progress
- Payment schedule
- Handover date
- Delay clauses
- Termination provisions
- Assignment conditions
- Service-charge estimate
- Defect-liability period
- Post-handover instalments
DLD’s Dubai REST platform provides project information such as completion percentage, project images, escrow-account numbers and payments due.
Do not send off-plan instalments to a salesperson’s personal account or an unexplained third-party company.
Ready-Property Due Diligence
Before purchasing a completed unit, check:
- Title-deed validity
- Seller identity
- Mortgage status
- Existing tenancy
- Rent-payment schedule
- Service-charge balance
- Maintenance history
- Air-conditioning
- Water damage
- Parking
- Building management
- Planned nearby construction
- Developer NOC
- Vacant-possession terms
For a tenanted property, understand the legal and financial effect of the existing lease. The advertised “market rent” may be irrelevant if the tenant is paying a different registered amount.
Exit Strategy
A good investment should have a plausible exit before it is purchased.
Consider:
- Likely future buyer
- Transaction volume
- Comparable supply
- Holding period
- Mortgage balance
- Developer resale restrictions
- Sale costs
- Currency conversion
- Capital-gains tax in the home country
- Time needed to sell
Potential exit audiences include:
- Owner-occupiers
- Local investors
- International investors
- Holiday-home operators
- Families
- Luxury buyers
Highly distinctive properties can achieve strong prices but may have a smaller buyer pool. Smaller standard units may sell more easily but face more competition.
Main Risks for International Investors
Market-cycle risk
Dubai property prices and rents can rise and fall.
Supply risk
New developments may compete for tenants and future buyers.
Developer risk
Off-plan projects can face delays, specification changes or execution problems.
Currency risk
Home-currency returns may differ from dirham returns.
Remote-management risk
Poor property management can reduce income and damage the asset.
Service-charge risk
Operating costs may increase and reduce net yield.
Financing risk
Interest rates, valuation shortfalls or refinancing conditions may change.
Liquidity risk
Property cannot always be sold quickly at the desired price.
Compliance risk
Incorrect licensing, rental or tax treatment can create penalties and disruption.
Concentration risk
Using most of an investor’s capital for one property creates exposure to a single asset, building and market.
International Investor Checklist
Strategy
- Define income, growth or personal-use objective
- Set the intended holding period
- Decide between ready and off-plan
- Choose long-term or short-term rental
- Model the exit
Financial analysis
- Compare registered prices
- Verify realistic rent
- Calculate gross and net yield
- Include vacancy
- Include service charges
- Include management and maintenance
- Allow for currency movements
- Stress-test mortgage repayments
Legal and property checks
- Confirm foreign-ownership eligibility
- Verify broker and permit
- Verify title deed or project
- Review the contract
- Confirm mortgage status
- Check tenancy
- Inspect the property
- Verify off-plan escrow
Transaction
- Prepare identification
- Document source of funds
- Obtain mortgage pre-approval
- Verify payment details
- Obtain the developer NOC
- Complete DLD registration
- Verify the electronic title deed
Post-purchase
- Arrange insurance
- Appoint management
- Register the tenancy
- Maintain repair reserves
- Track actual net return
- Review tax reporting
- Reassess the exit strategy annually
Frequently Asked Questions
Can an international investor buy Dubai property without residency?
Yes. Foreign non-residents may buy eligible property in designated foreign-ownership areas.
Is there a minimum investment amount?
There is no universal minimum price simply to own eligible property. Minimum values apply to certain residency and financing programmes.
Can an overseas investor obtain a mortgage?
Potentially. Some UAE banks offer non-resident mortgages, but lender, nationality, income and property restrictions apply.
Is rental income guaranteed?
No. Rental performance depends on the unit, location, condition, management, pricing and market demand.
Is off-plan property better for international investors?
Not automatically. Off-plan offers staged payments but creates completion, resale and market risks. Ready property provides more immediate evidence of quality and rent.
Do I need a UAE bank account?
Not for every cash purchase, but one can simplify payments, mortgage servicing, rental income and ongoing expenses.
Can I manage the property from another country?
Yes. A licensed property manager can handle leasing, rent collection, maintenance and inspections.
Can I use the property as a holiday home?
Potentially, subject to Dubai’s holiday-home licensing and operating requirements.
Does buying property provide a Golden Visa?
Not automatically. Eligible real estate investment of at least AED 2 million may support an application, subject to current rules.
Is Dubai property tax-free?
Dubai does not levy a conventional annual residential property tax, but transaction costs, VAT in applicable cases and home-country taxes may still apply.
Should I buy personally or through a company?
Personal ownership is often simpler for one residential property. Company ownership may suit portfolios or joint investors but adds tax, licensing, banking and compliance obligations.
What is the biggest mistake international investors make?
Buying from marketing projections without independently verifying the price, rent, service charges, property condition and exit liquidity.
Final Verdict
Buying Dubai property as an international investor can provide access to rental income, long-term growth potential and one of the world’s most internationally connected real estate markets.
The market’s accessibility should not replace due diligence. Investors should compare registered transaction evidence, calculate net rather than gross returns, verify all payment instructions and understand how currency, financing, tax and future supply affect the investment.
The strongest Dubai property investment is not necessarily the most luxurious unit or the newest development. It is the property purchased at a sensible price, supported by sustainable demand, manageable costs and a realistic exit strategy.
At HAMZ, we believe international property investment should begin with evidence, not excitement. Every Dubai opportunity should be measured against verified pricing, sustainable tenant demand, complete ownership costs, realistic net returns and a clear exit strategy before capital is committed.
Read Also: Can a Company Buy Property in Dubai? Complete Corporate Buyer’s Guide